Are Bioherbicides Ready to Replace Conventional Weed Control in 2026
As weed resistance, residue scrutiny, and sustainability targets intensify across global agriculture, bioherbicides are moving from niche interest to strategic consideration. But are they ready to replace conventional weed control in 2026? For decision-makers across crop protection and agricultural input markets, the answer depends less on ideology than on field performance, formulation stability, regulatory acceptance, supply reliability, and cost-effectiveness in real farming systems.
The short answer is no: bioherbicides are not ready to broadly replace conventional weed control across major cropping systems in 2026. But that is not the most useful conclusion for the market. A more accurate assessment is that bioherbicides are becoming commercially relevant in specific segments where resistance pressure, residue expectations, registration barriers for synthetic actives, and integrated weed management needs are reshaping buying behavior. For manufacturers, distributors, and agri-input investors, the question is no longer whether this category matters. It is where it can work, how fast it can scale, and what risks remain unresolved.
Why the market is taking bioherbicides more seriously now
Interest in biological weed control has existed for years, but the commercial context has changed. Weed control is no longer judged only by kill rate and per-hectare cost. Buyers now evaluate performance through a wider lens: resistance management, pre-harvest intervals, residue expectations in export crops, compatibility with regenerative or low-residue farming systems, worker safety, and regulatory uncertainty around conventional herbicide portfolios.
Three market forces are especially important.
The first is herbicide resistance. In many regions, repeated use of the same modes of action has reduced the reliability of conventional programs. This does not automatically make bioherbicides superior, but it raises the value of additional tools, especially in integrated systems where rotational diversity matters.
The second is regulatory and public scrutiny. The pressure is not uniform worldwide, but active ingredients used in broadacre weed control face continuing review in several markets. Even where outright bans do not occur, labeling restrictions, buffer requirements, application timing limits, and residue concerns can reduce commercial flexibility. That creates space for alternatives, particularly in horticulture, specialty crops, and controlled-environment agriculture.
The third is sustainability positioning across the food chain. Retailers, food processors, and exporters increasingly ask upstream suppliers to demonstrate lower environmental load, reduced residue exposure, or more regenerative production practices. In practice, these requests often translate into incremental substitution rather than full replacement. Bioherbicides fit this trend better as a portfolio component than as a universal standalone solution.
What bioherbicides can realistically do in 2026
The bioherbicide category is broad and often misunderstood. It can include microbial products, fermentation-based metabolites, plant-derived active substances, and other biologically sourced weed suppression solutions. Their commercial value does not lie in mimicking every feature of synthetic herbicides. In many cases, their value lies in targeted suppression, improved fit for sensitive production systems, or use in combination with mechanical, cultural, and chemical controls.
In 2026, the strongest opportunities are likely to remain in areas where precision matters more than universal knockdown power. These include:
- High-value horticultural crops where residue management carries premium importance
- Organic and transitional farming systems where synthetic options are structurally limited
- Inter-row, directed spray, or localized weed management programs
- Resistance management programs seeking mode-of-action diversification
- Greenhouse, nursery, turf, and non-crop vegetation settings where application conditions can be better controlled
That matters commercially because the path to adoption is not likely to start in the largest-acreage commodity markets. It is more likely to scale first in systems where growers can tolerate higher input costs if the product reduces a larger business risk, such as rejection due to residues, limited labor availability for hand weeding, or loss of market access.
For executives evaluating market timing, this distinction is critical. A category does not need to dominate row-crop weed control to become strategically important. It only needs to become indispensable in enough profitable segments.
Why replacement is still difficult at field level
The main barrier is not market interest. It is biological and operational consistency.
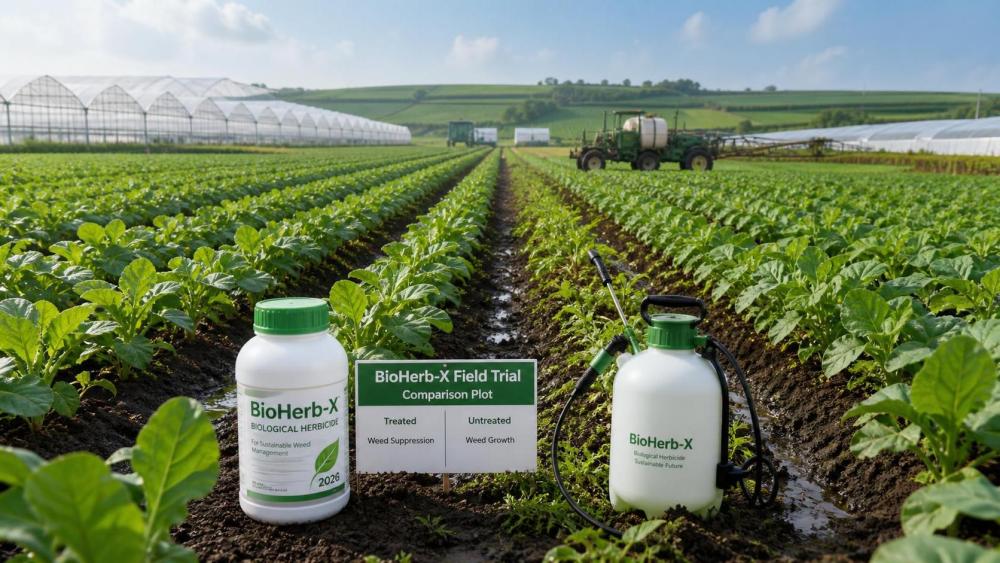
Conventional herbicides earned their market position because they deliver relatively predictable control across varied conditions when used correctly. Bioherbicides often face a narrower operating window. Their performance may depend more heavily on humidity, temperature, weed growth stage, spray coverage, water quality, sunlight exposure, and post-application environmental conditions. A product that performs well in one region or season may produce uneven results in another.
This is where many commercial discussions become too simplistic. Buyers do not reject bioherbicides because they dislike biological solutions. They reject products that introduce uncertainty into already narrow farming margins.
Several operational constraints remain significant:
- Slower or less visually dramatic weed control, which can reduce grower confidence
- Narrower weed spectrum compared with broad-spectrum synthetics
- Greater sensitivity to application timing and environmental conditions
- Shorter shelf life or more demanding storage conditions for some formulations
- Potential incompatibility with common tank-mix partners or adjuvant systems
- More complex field education requirements for distributors and agronomists
For business decision-makers, this means the commercial challenge is not only product efficacy. It is implementation reliability across the value chain. If distributors cannot explain use conditions clearly, or if growers treat the product like a drop-in replacement for a conventional herbicide, disappointment is likely.
Formulation quality will decide who scales and who stalls
In the next phase of this market, formulation science may matter more than headline claims about biological origin. A promising active concept is not enough. Commercial success depends on whether the product remains stable in storage, survives transport, delivers consistent concentration, sprays evenly, adheres to target surfaces, and performs within realistic on-farm workflows.
This is especially relevant for biological products because decision-makers often underestimate how much formulation determines field outcomes. Questions that procurement and technical teams should be asking include:
- What is the product’s storage stability under real distribution conditions?
- How sensitive is efficacy to pH, water hardness, UV exposure, or temperature swings?
- Can the formulation support acceptable shelf life in export channels?
- Is performance dependent on specialized adjuvants or application protocols?
- How reproducible is batch quality at industrial scale?
These are not secondary issues. They are central to whether bioherbicides can move from pilot interest to repeat sales. In conventional crop protection, buyers often assume formulation maturity. In biological weed control, that assumption is still unsafe.
Regulation may help adoption, but it will not eliminate performance risk
Many market observers assume that tighter regulation on conventional herbicides will automatically accelerate replacement. That view is incomplete.
Regulatory pressure can certainly create openings. Biological products are often better aligned with lower-toxicity positioning, and in some jurisdictions they may benefit from more favorable review pathways than conventional synthetic chemistry. But easier registration does not guarantee faster market penetration. Buyers still need proof of agronomic value, and growers still need confidence that using the product will not increase total weed control cost or yield risk.
Regulatory reality also varies by country. Registration requirements, accepted claims, data expectations, and biopesticide definitions are not harmonized globally. Companies attempting to build cross-border portfolios in bioherbicides must account for fragmented approval pathways, documentation requirements, and local labeling constraints. Any assumption that one successful registration will unlock global scale is risky.
Where regulation matters most commercially is in segment prioritization. Bioherbicides become more attractive where conventional options are being narrowed, where export residue standards are tightening, or where sustainability-linked procurement standards begin influencing grower input choices. That is a stronger market signal than generic discussion about “green agriculture.”
Cost competitiveness is more complicated than price per liter
One of the most common mistakes in evaluating bioherbicides is comparing them to synthetic herbicides only on nominal product price. That misses the real economics.
Decision-makers should compare total weed management cost under realistic use conditions. That includes application frequency, labor requirements, compatibility with existing spray programs, expected efficacy consistency, risk of retreatment, crop selectivity, and any commercial premium attached to lower-residue production.
In broadacre cereals, oilseeds, or soybean systems, bioherbicides still face a difficult economics case if they require multiple passes or deliver inconsistent suppression under variable field conditions. In contrast, in fruit, vegetables, herbs, seed crops, or protected cultivation, the economics may improve sharply if the product helps avoid residue issues, lowers hand-weeding intensity, or supports compliance with buyer standards.
This is why 2026 is unlikely to be the year of universal replacement, but it could be a strong year for selective substitution. Margin structure matters. Cropping system matters. Market channel matters.
Supply chain maturity is still uneven
For importers, distributors, and private-label companies, supply risk remains one of the least discussed issues. A bioherbicide portfolio is only as reliable as its upstream production system.
Some products depend on microbial fermentation, botanical extraction, or specialized downstream stabilization processes that may be more variable than mature synthetic production chains. Raw material consistency, contamination control, active concentration drift, and cold-chain or storage management can all affect the final business case.
Supplier assessment therefore needs to go beyond brochure claims. Companies should verify manufacturing reproducibility, quality documentation, packaging suitability, transport stability, and technical support capacity. If a supplier cannot explain how the product behaves after 60 to 90 days in real warehouse conditions, commercial confidence should remain limited.
This is particularly important for companies planning expansion into multiple climate zones. A product stable in one domestic market may not remain commercially robust in tropical distribution environments or under long shipping timelines.
What the likely 2026 market looks like
The most probable scenario for 2026 is not replacement, but rebalancing.
Conventional herbicides will remain the foundation of weed management in large-scale commodity agriculture because they still offer broad-spectrum activity, operational simplicity, and established economics. Bioherbicides will expand, but mainly where they solve a specific commercial problem better than conventional options or where they complement reduced-chemical programs.
That suggests several likely market outcomes:
- More partnerships between biological technology developers and established crop protection distributors
- Increased emphasis on integrated weed management rather than standalone biological substitution
- Faster uptake in specialty crops than in broadacre row crops
- More investment in formulation improvement, adjuvant compatibility, and field-use guidance
- Higher scrutiny from buyers on real-world efficacy data rather than greenhouse or small-plot claims alone
It also suggests that the winners may not be the companies with the most ambitious replacement narrative. They may be the ones that position bioherbicides honestly: as targeted tools within a broader agronomic system.
How decision-makers should evaluate the category now
For companies deciding whether to invest, distribute, source, or monitor bioherbicides in 2026, the most practical approach is to avoid binary thinking.
The category should not be judged by asking whether it can replace all conventional weed control. That sets the wrong benchmark and obscures more immediate opportunities. A better set of questions would be:
- Which crops and weed scenarios show recurring pressure that conventional programs are not solving cleanly?
- Where do residue, resistance, or market access issues justify alternative solutions?
- Which candidate products have formulation stability and supply-chain discipline strong enough for repeat business?
- Can the product fit existing agronomic workflows without excessive retraining or multiple corrective passes?
- Is the commercial upside coming from input substitution, premium crop positioning, or regulatory risk reduction?
Companies that ask these questions will make better decisions than those chasing general sustainability headlines.
So, are bioherbicides ready to replace conventional weed control in 2026? At full market scale, no. In selected segments, increasingly yes. The strategic takeaway is not that conventional herbicides are about to disappear. It is that weed control portfolios are becoming more diversified, more regulation-sensitive, and more application-specific. Businesses that understand where bioherbicides genuinely fit will be in a stronger position than those waiting for a single technology to overturn the market all at once.
Related News
 Antioxidants & Natural PreservativesHow Propionates Extend Shelf Life While Meeting Food Safety RequirementsPropionates extend shelf life by controlling mold in bakery and moisture-sensitive foods. Explore smart dosage, compliance, supplier quality, and safer distribution strategies.MORE+
 Maillard Reaction Savory FlavorsHow Concentrated Flavor Pastes Solve Batch-to-Batch Flavor VariationConcentrated flavor pastes help manufacturers reduce batch-to-batch variation with precise dosing, reliable dispersion, and stronger sensory consistency.MORE+
 Nano-microcapsule FormulationsWhat to Verify When Choosing a Cyclodextrin Inclusion Complexes ManufacturerChoose a cyclodextrin inclusion complexes manufacturer with confidence: verify complexation evidence, loading, stability, process control, and batch consistency.MORE+
 Zero-Calorie Sweeteners & AcidulantsHow Liquid Flavors for Soft Drinks Improve Taste Consistency at ScaleLiquid flavors for soft drinks help manufacturers achieve reliable taste consistency at scale through accurate dosing, controlled mixing, stability management, and sensory quality control.MORE+
 Heavy-duty Industrial DegreasersHow to Evaluate a Degreasing Surfactants Factory for Industrial CleaningDegreasing surfactants factory evaluation guide: compare cleaning performance, foam control, quality consistency, documentation, compatibility, and supply reliability.MORE+
 Zero-Calorie Sweeteners & AcidulantsWhat to Check When Choosing a Saccharin Sodium Supplier for Global OrdersChoose a reliable saccharin sodium supplier for global orders. Learn how to assess quality, documentation, packaging, export readiness, and total landed reliability.MORE+
 Non-ionic Surfactants & DefoamersHow Non Ionic Industrial Dispersants Prevent Sedimentation in Water Based FormulasNon ionic industrial dispersants help prevent sedimentation in water-based formulas. Discover practical controls for stable, redispersible industrial suspensions.MORE+
 Antioxidants & Natural PreservativesHow Oxidation Resistant Flavor Encapsulates Protect Taste During ProcessingOxidation resistant flavor encapsulates help protect delicate taste through heat, oxygen, and storage. Discover how to improve flavor retention, release, and processing consistency.MORE+
 Polymer-Coated Water Soluble NPKHow to Choose Resin Coated NPK Fertilizers for Efficient Nutrient ReleaseResin Coated NPK Fertilizers: learn how to match release duration, nutrient profiles, granule quality, and supplier reliability to your crop programme for better efficiency and lower costs.MORE+
 Microencapsulated FragrancesHow Cyclodextrin Inclusion Complexes for Fragrances Improve Scent LongevityCyclodextrin inclusion complexes for fragrances enhance scent longevity through controlled release, improved stability, and application-specific performance. Discover how to optimize lasting aroma.MORE+
 Hydrocolloids & EmulsifiersHow Sodium Alginate for Textile Printing Improves Paste ControlSodium alginate for textile printing improves paste control, sharpens print definition, and supports reliable reactive dye production. Explore key formulation insights.MORE+
 Antioxidants & Natural PreservativesHow to Choose Green Tea Extract for Stable, Consistent FormulationsGreen Tea Extract selection guide for stable, consistent formulations—compare standardization, solubility, carriers, stability, and batch quality with confidence.MORE+
 Maillard Reaction Savory FlavorsHow Reaction Flavors Create Richer Taste in Baked and Savory FoodsReaction Flavors bring roasted, toasted, and savory depth to bakery, snacks, sauces, and plant-based foods. Learn how to select profiles that perform after processing.MORE+
 Maillard Reaction Savory FlavorsCan Flavor Bases Withstand High-Temperature Baking Without Losing Flavor?Can flavor bases withstand high temperature baking? Discover how heat, moisture, encapsulation, and formula design affect flavor retention in baked goods.MORE+
 EPA FIFRA & FDA GRAS RegsHow High Intensity Sweeteners for Tabletop Use Meet Labeling StandardsHigh intensity sweeteners for tabletop use: discover how accurate labeling, serving claims, ingredient lists, nutrition data, and regional rules support compliant market entry.MORE+
 Antioxidants & Natural PreservativesIs TBHQ for Shortening Safe and Effective for Longer Shelf Life?TBHQ for shortening: discover how safe, compliant antioxidant use can reduce rancidity, protect quality, and support longer shelf life through validated controls.MORE+
 Non-ionic Surfactants & DefoamersWhat to Check Before Choosing an Electronic Cleaning Chemicals FactoryElectronic cleaning chemicals factory selection guide: evaluate purity, compatibility, residue control, quality consistency, documentation, and total process cost.MORE+
 Hydrocolloids & EmulsifiersHow Thickening Agents Improve Texture and Stability in Food FormulasThickening Agents improve food texture, stability, suspension, and mouthfeel. Discover how to select the right solution for sauces, beverages, desserts, and more.MORE+
 Ultra-pure Semiconductor CleanersSelecting Low Residue Semiconductor Wafer Cleaners for Critical ProcessesLow residue semiconductor wafer cleaners: learn how to select compatible, rinse-ready solutions that protect critical processes, reduce contamination risk, and support reliable yield.MORE+
 Synthesis CAPEX & Yield ROIHow to Evaluate a Semiconductor Process Cleaners Manufacturer for YieldSemiconductor process cleaners manufacturer evaluation guide: assess purity, lot consistency, rinse behavior, compatibility, and change control to protect wafer yield.MORE+
 EPA FIFRA & FDA GRAS RegsWhat to Check Before Choosing a Sucralose Supplier for Food ProductionChoose a reliable sucralose supplier with confidence. Explore essential checks for quality, compliance, batch consistency, traceability, packaging, and supply reliability.MORE+
 Polymer-Coated Water Soluble NPKWhich Specialty Fertilizers Best Support High-Value Crop Production?Specialty Fertilizers for high-value crops: compare controlled-release, water-soluble, micronutrient, and biostimulant options for precision, quality, and reliable results.MORE+
 Supercritical CO2 Essential OilsHow to Evaluate a Natural Aroma Chemicals Manufacturer for Reliable SupplyNatural aroma chemicals manufacturer evaluation guide: verify traceability, batch consistency, compliance, application support, capacity, and total cost to secure reliable supply.MORE+
 Chelated Trace Element FertilizersChoosing Chelated Magnesium Fertilizers for More Efficient Crop NutritionChelated Magnesium Fertilizers: learn how to match product stability, water quality, and application methods for efficient crop nutrition and stronger results.MORE+
 Targeted Bio-pesticides & APIsHow Organic Botanical Insecticides Can Improve Integrated Pest ManagementOrganic botanical insecticides can strengthen IPM through targeted pest control, smarter monitoring, safer application, and better protection of crops and beneficial insects.MORE+
 Hydrocolloids & EmulsifiersHow Hydrocolloid Stabilizer Blends Keep Sauces Smooth and StableHydrocolloid stabilizer blends for sauces help prevent separation, improve texture, and deliver smooth, reliable performance from production to shelf.MORE+
 Non-ionic Surfactants & DefoamersWhat to Check Before Buying Low Residue Surfactants WholesaleLow residue surfactants wholesale: learn what to check for composition, rinse performance, batch consistency, and supplier reliability before placing bulk orders.MORE+
 Non-ionic Surfactants & DefoamersWhy Non Ionic Semiconductor Surfactants Help Control Particle DefectsNon ionic semiconductor surfactants help reduce particle defects through better wetting, dispersion, rinse control, and high-purity process qualification.MORE+
 Ultra-pure Semiconductor CleanersHow to Evaluate a Semiconductor Cleaners Factory for Ultra-Pure SupplySemiconductor cleaners factory evaluation guide: verify ultra-pure specifications, contamination controls, packaging integrity, and supply resilience before qualification.MORE+
 Hydrocolloids & EmulsifiersHow Cold Soluble Hydrocolloid Systems Improve Instant Sauce TextureCold soluble hydrocolloid systems help instant sauces achieve smooth, stable texture, controlled viscosity, and better suspension—learn how to optimize hydration and mouthfeel.MORE+
 Non-ionic Surfactants & DefoamersHow Can an Alkaline Degreasers Exporter Support Global Cleaning SupplyAn alkaline degreasers exporter supports global cleaning supply with stable formulations, tailored performance, compliant packaging, and reliable technical guidance.MORE+
 Supercritical CO2 Essential OilsWhat Should You Know About Natural Aroma Chemicals and Their UsesNatural Aroma Chemicals: explore how to select, test, and formulate natural aroma ingredients for fragrances, food, personal care, and home care products.MORE+
 Zero-Calorie Sweeteners & AcidulantsAre High Intensity Sweeteners for Tabletop Use Right for Your ProductExplore high intensity sweeteners for tabletop use: compare taste, carriers, serving cost, stability, packaging, and compliance to build a successful product.MORE+
 Heavy-duty Industrial DegreasersHow to Choose Parts Wash Cleaners for Automotive Components Without DamageParts wash cleaners for automotive components: learn how to remove oils and residues while protecting metals, plastics, seals, coatings, and downstream assembly performance.MORE+
 Hydrocolloids & EmulsifiersHow Does Locust Bean Gum Powder Improve Texture in Clean-Label FoodsLocust bean gum powder improves clean-label food texture with smoother body, better water control, and reliable stability across dairy alternatives, sauces, bakery, and frozen desserts.MORE+
 Antioxidants & Natural PreservativesWhy Ferulic Acid Matters in Modern Antioxidant FormulationsFerulic Acid helps modern formulations enhance oxidative stability, protect sensitive ingredients, and support differentiated product performance across key applications.MORE+
 Chelated Trace Element FertilizersHow to Use Triple Superphosphate for Phosphorus Deficient SoilTriple superphosphate for phosphorus deficient soil: learn soil testing, precise rates, smart placement, and pH management to improve crop phosphorus uptake.MORE+
 Hydrocolloids & EmulsifiersWhat Determines Konjac Gum Bulk Price for Reliable Cost PlanningKonjac gum bulk price depends on grade, glucomannan content, logistics, and functional performance. Learn how to compare quotes and plan reliable landed costs.MORE+
 Hydrocolloids & EmulsifiersHow to Choose Food Stabilizers for Dairy Drinks Without Texture IssuesFood stabilizers for dairy drinks: learn how to prevent separation, sediment, and gummy texture with the right protein-compatible system and process controls.MORE+
 Microencapsulated FragrancesHow Microencapsulated Fragrance Systems Improve Long-Lasting ScentMicroencapsulated fragrance systems protect scent, control release triggers, and deliver longer-lasting fragrance across laundry, personal care, and cleaning products.MORE+